SMARTER FINANCIAL DECISIONS

Finance That Moves Your Plans Forward

Explore personal, business, home, and education loan options with complete clarity. Compare repayment scenarios, calculate accurate EMIs, and understand eligibility requirements before submitting any lender application.

Clear Information

Independent guides and fee breakdown analysis.

Flexible Options

Compare varying loan tenures and monthly impact.

Transparent Guidance

Learn key borrower rights before signing agreements.

Illustrative Overview Plan With Confidence

Balanced Repayment

Lower tenure keeps total interest payments modest while maintaining comfortable monthly commitments.

Illustrative Loan Amount ₹ 5,00,000
Repayment Tenure 36 Months (3 Yrs)
Estimated Monthly EMI ₹ 16,250 / mo

*All figures shown in this panel are illustrative examples for planning demonstration purposes only. Actual rates depend upon individual lender review.

PORTFOLIO OVERVIEW

Four Distinct Financing Categories

Different financial goals require tailored structures. Review typical requirements, tenure parameters, and eligibility considerations across our primary lending categories. Terms vary by accredited partner institutions.

Personal Loans

Unsecured Personal Financing

Designed for urgent medical outlays, scheduled home renovation, higher education bridging, or planned family events without collateral requirements.

Tenure: 12 – 60 Months Collateral: None Required

Home Loans

Residential Housing Finance

Long-term financing solutions for buying ready apartments, constructing on private plots, or transferring existing home balances to reduce interest.

Tenure: Up to 30 Years Security: Property Mortgage

Business Loans

Commercial Expansion Capital

Working capital lines, machinery procurement, and scale-up facilities to support growing enterprises with proven operational cash flows.

Tenure: 12 – 84 Months Basis: Financial Turnovers

Education Loans

Academic Career Support

Funding academic tuition, university lodging, travel, and research supplies for domestic and accredited global postgraduate and undergraduate degrees.

Grace Period: Course + 6-12 Mo Co-borrower: Parent / Guardian
DISCOVERY TOOL

Loan Recommendation Finder

Answer 3 quick preferences to view personalized informational guidance and typical borrowing pathways.

₹ 4,00,000
₹ 50,000 ₹ 25,00,000 ₹ 75,00,000
Summary & Recommendation
Category: Personal Expenses
Target Amount: ₹ 4,00,000
Desired Tenure: 36 Months (3 Years)
For personal expenses over 36 months, prioritize lenders with zero prepayment penalties to preserve flexibility if your cash flows improve.

Informational tool only. Recommendations do not constitute an official loan offer, pre-approval, or guarantee of terms from any partner institution.

FINANCIAL PLANNING TOOL

Equated Monthly Installment (EMI) Calculator

Calculate your estimated monthly commitment and interest proportion using standard reducing-balance actuarial formulas.

Loan Parameters

₹
₹ 10,000 ₹ 50,00,000 ₹ 1,00,00,000
%
1% 15% 30%
Yr
1 Year 15 Years 30 Years
Estimated Monthly Payment (EMI)
₹ 16,252
Payable on reducing balance schedule
Total Principal
₹ 5,00,000
Total Estimated Interest
₹ 85,066
Overall Repayment Amount
₹ 5,85,066
Principal (85%)
Interest (15%)
Notice: These calculations are estimates for planning purposes only. Actual repayments may vary based on lender terms, fees, taxes, and other charges.
STRUCTURED PROCESS

How Loan Evaluation Works

Four methodical stages from initial product assessment to verified loan disbursement.

01

Choose a Loan

Determine your exact capital requirements, repayment capabilities, and whether personal, home, or business credit best aligns with your goals.

02

Review Eligibility

Evaluate essential credit benchmarks, age thresholds, minimum verifiable income guidelines, and debt-to-income limits required by lenders.

03

Compare Terms

Scrutinize processing fees, prepayment lock-ins, variable rate reset periods, and insurance requirements across prospective accredited providers.

04

Apply With a Provider

Submit authenticated KYC and financial statements directly via the official lender portal for formal underwriting and contract execution.

SIDE-BY-SIDE MATRIX

Comprehensive Loan Comparison

Understand how collateral requirements, repayment tenure horizons, and documentation standards differ across primary retail borrowing segments.

Loan Type Typical Purpose Repayment Considerations Common Documentation Action
Personal Loan
Medical emergency, debt consolidation, wedding, relocation Fixed EMIs over 1 to 5 years; zero asset collateral; strict credit score weight PAN, Aadhaar, 3 months salary slips, 6 months bank statement Details
Home Loan
Apartment purchase, independent villa construction, plot finance 10 to 30 years repayment horizon; property mortgaged; tax benefits applicable Title deed, approved plan, tax receipts, form 16, income tax returns Details
Business Loan
Working capital buffer, inventory procurement, commercial machinery Structured around seasonal cash flows; audited balance sheets required GST returns, 2 years audited ITR, business registration certificate Details
Education Loan
Tuition, laboratory charges, university dormitory, international travel Moratorium period during studies + 6-12 months post completion Admission confirmation letter, fee breakdown, co-applicant KYC & salary Details
*Swipe horizontally on mobile devices to view all comparison criteria. Specifications depend on respective lending partner underwriting policies.
TRANSPARENT PLATFORM

Empowering Clear & Objective Borrowing Choices

We believe financial decisions should never be based on high-pressure sales pitches or obscure fee structures. Corvenzaar Finance delivers unbiased tools, transparent educational resources, and practical mathematical estimators to help you evaluate loans with calm clarity.

Launch Planning Tools

Clear Financial Information

Unbiased editorial guides detailing the true cost of credit without promotional puffery or misleading zero-interest marketing gimmicks.

Practical EMI Planning

Actuarial calculation models simulating principal reduction, interest amortization curves, and early prepayment savings.

Loan Comparison Guidance

Systematic matrix analysis comparing processing fees, foreclosure rules, and rate adjustment benchmarks across loan types.

Application Preparation

Interactive compliance checklists allowing prospective borrowers to assemble verified verification paperwork prior to filing.

APPLICATION READINESS

Eligibility Criteria & Documentation Checklist

Understand the baseline benchmarks lenders evaluate and prepare required KYC records locally in your browser.

Underwriting Evaluation Factors

Financial institutions generally evaluate applications based on five primary prudential pillars:

  • 1
    Age & Legal Residency: Applicants must typically be between 21 and 65 years old with verifiable citizen or residential documentation.
  • 2
    Income & Employment Stability: A steady history of continuous salaried employment or minimum 2-3 years active business operations.
  • 3
    Fixed Obligation to Income Ratio (FOIR): Total current monthly loan repayments should ideally remain below 40%–50% of net monthly income.
  • 4
    Credit History & Bureau Score: A clean repayment record with a credit bureau score of 720+ unlocks favorable interest terms.
  • 5
    Loan-to-Value (LTV) for Secured Borrowing: Housing and collateral loans require a mandatory borrower margin contribution (10% to 25%).
*Criteria vary across banks and NBFCs. Satisfying minimum benchmarks does not imply mandatory approval.

Document Checklist

0 of 5 Ready

Check off items you have organized. Your progress remains saved locally on this device.

DEBT STRATEGY

Prudent Loan Repayment Architecture

Borrowing wisely requires understanding how interest accumulates over time. Always focus on total interest expenditure rather than just monthly installment affordability.

01

Prioritize Monthly Buffer Room

Avoid borrowing at maximum limits.

Keep your total debt commitments under 35% of monthly disposable earnings. This preserves vital financial leeway to absorb unexpected medical or maintenance shocks without defaulting.

02

Analyze Total Cost of Borrowing

Look beyond the seductive low monthly installment.

Stretching loan tenure over extra years noticeably reduces the monthly EMI, but dramatically inflates the cumulative interest disbursed to the lender. Shorten tenure wherever feasible.

03

Verify Prepayment Penalties

Safeguard your future early payoff rights.

Ensure your lending agreement permits partial lump-sum repayments without penal fees. Under RBI directives, floating-rate personal loans to individuals generally carry zero prepayment penalties.

Live Illustration: 3 Years vs. 5 Years

Examine how choosing a 36-month tenure versus a 60-month tenure on a ₹ 5,00,000 personal loan at 11% interest saves you over ₹ 65,000 in net interest fees.

60 Months (Extended)
₹ 10,871 / mo
Total Interest: ₹ 1,52,273
EDITORIAL & ADVISORY

Financial Guides & Educational Resources

Comprehensive handbooks authored to simplify banking terminology, interest rate dynamics, and consumer rights. Click any guide to view the full in-depth article.

Fixed vs. Floating Interest Rates: Choosing the Right Risk Profile

An analysis of when locking in a predictable fixed rate makes sense versus leveraging floating rates during anticipated central bank easing cycles.

Read Article →

How to Prepare for a Formal Loan Application & Protect Your Score

Preventing hard credit bureau inquiry damage, resolving discrepancies in credit reports, and organizing income files before lender submission.

Read Article →

Hidden Loan Fees, Processing Costs & Legal Penalties Uncovered

A line-by-line inspection of documentation fees, stamp duty charges, legal vetting costs, and bounce penalty structures commonly levied by lenders.

Read Article →
COMMON QUERIES

Frequently Asked Questions

Clear, transparent explanations addressing common uncertainties regarding retail lending, eligibility assessment, interest compounding, and repayment obligations.

An EMI is a fixed monthly dollar or rupee amount paid by a borrower to a financial lender on a predetermined calendar date. Each installment comprises both principal repayment and accrued interest components calculated on a reducing balance basis.

Modern reputable lenders utilize the reducing balance methodology: interest is computed only on the outstanding principal balance each month rather than the original sanctioned amount, resulting in progressively declining interest costs as you repay.

Underwriters scrutinize credit bureau scores (ideally 720+), net disposable income, existing debt commitments (FOIR ratio), job tenure stability, employer category reputation, and age.

Yes. Many retail loan products permit prepayments. For individual borrowers with floating-rate retail loans, regulatory guidelines prohibit lenders from charging foreclosure penalties. Always review terms for fixed-rate commercial loans.

Scrutinize upfront loan processing fees, legal documentation or title search fees, stamp duty charges, loan cancellation charges, and penal interest terms for delayed payments.

Compare the Annual Percentage Rate (APR) rather than simple headline nominal rates. APR factors in processing fees, administrative charges, and mandatory insurance costs alongside interest.

No. Corvenzaar Finance provides client-side informational calculators and simulated guidance. We do not perform credit bureau pulls, ensuring zero impact on your credit profile.

Defaulting or delaying an EMI incurs penal interest, bank bounce charges, and negative credit bureau reporting that can damage your borrowing eligibility for years. Always contact your lender promptly to discuss restructuring if distress arises.

CUSTOMER SUPPORT

Connect With Our Educational Advisory Team

Have inquiries regarding loan calculators or educational resources? Reach out through our verified support desk.

Need Help Understanding Your Options?

Our financial educational specialists are available to answer general queries regarding calculator math, checklist readiness, and loan terminology.

Email Support Desk
Hours of Availability
Mon – Fri, 9:30 AM – 6:30 PM IST
Notice: The email and phone numbers above are demonstration placeholders. In a live deployment, replace these with your authentic registered customer service channels.

Privacy Policy

Last Updated: October 2026 • Reference: Corvenzaar-PRV-2026

1. Educational Scope & Data Minimization

At Corvenzaar Finance, we treat your privacy with rigorous care. This website serves as an educational and mathematical financial planning portal. We do not require account registration, social logins, or the transmission of identity credentials to utilize our calculators or reading resources.

2. Local Client-Side Calculation Math

All computations performed within the EMI Calculator, Loan Finder, and Document Readiness Checklist execute entirely within your local browser environment. No financial inputs, desired borrowing amounts, or checklist items are stored on remote servers.

3. Contact Enquiries

When you submit an advisory inquiry through our contact form, your name, email, and message are used solely to generate a localized response. We do not sell, rent, or distribute contact lists to third-party marketing companies, telemarketers, or unverified lenders.

4. Cookies & Web Tracking

This website uses only essential session mechanisms to enable seamless client-side view navigation. We do not employ third-party behavioral tracking pixels or intrusive advertising cookies.

5. Inquiries Regarding Privacy

For questions regarding data processing standards or demonstration website terms, please communicate via our contact desk.

Terms & Conditions

Effective Date: October 2026 • Version 2.4

1. Acceptance of Terms

By accessing and navigating Corvenzaar Finance, you agree to comply with and be bound by these Terms and Conditions. If you do not accept these provisions in full, please discontinue website usage immediately.

2. Informational & Educational Nature

Corvenzaar Finance is not a licensed bank, non-banking financial company (NBFC), credit bureau, or direct lending institution. We do not directly issue loans, disburse funds, or underwrite credit risks. All content, calculators, and comparisons are created solely for informational, illustrative, and educational purposes.

3. No Substitute for Professional Financial Advice

Calculations generated by our tools should not be construed as binding loan offers, credit sanction letters, or legal counsel. Actual lending terms, interest rates, processing fees, and documentation mandates are established exclusively by accredited institutional providers at their sole discretion.

4. Intellectual Property

All proprietary editorial guides, computational formulas, logos, color schemas, and custom user interface layouts on Corvenzaar Finance are protected under applicable intellectual property laws. Unauthorized duplication or commercial re-distribution without written permission is prohibited.

Financial & Legal Disclaimer

Mandatory Regulatory Notice • Corvenzaar Finance

1. Non-Lending Entity Declaration

Corvenzaar Finance is an independent financial education and planning utility. We are not an intermediary licensed to approve or reject credit. We do not collect loan application fees, brokerage charges, or deposits.

2. Actuarial Formula Variance

Our EMI calculator implements the standard reducing-balance actuarial formula. While mathematically accurate, actual loan schedules generated by banks may diverge marginally due to differing month-end day-count conventions (30/360 vs. actual/365), compounding frequencies, and localized tax levies.

3. Responsible Borrowing Advice

Borrowers are strongly encouraged to inspect official sanction letters, understand prepayment terms, verify annual percentage rates (APR), and consult certified independent financial advisors prior to entering into legal loan commitments.

Contact Customer Support

Direct Inquiries • Advisory Office

Reach Our Educational Support Team

We are committed to providing prompt responses to queries concerning financial literacy, educational resources, and calculator tools.

Primary Email: [email protected] (Placeholder)

Telephone Line: +91 XXXXX XXXXX (Placeholder)

Operational Address: Corvenzaar Finance Headquarters, Financial District (Demonstration)

Operating Hours: Monday – Friday, 9:30 AM to 6:30 PM IST

To send an inquiry right away, please use the Homepage Contact Form.

Personal Loans — Comprehensive Overview

Product Category: Unsecured Retail Credit
Personal Finance and Lifestyle Planning

What is a Personal Loan?

A personal loan is an unsecured borrowing instrument that does not require you to pledge physical collateral such as real estate, gold, or investment securities. Funds may be deployed flexibly for wedding arrangements, urgent medical procedures, home repairs, or credit card debt consolidation.

Typical Eligibility Criteria

  • Applicant Age: Minimum 21 years up to 60 years at maturity.
  • Net Monthly Income: Usually ₹ 25,000+ for salaried corporate employees.
  • Credit Score: 720+ preferred for competitive interest rates.
  • Employment Stability: Minimum 1 year in present employment.

Key Precautions

Because personal loans are unsecured, lenders bear higher risk. Always evaluate processing fees (1%–3%) and verify if early foreclosure charges apply before finalizing agreements.

Borrowing Range ₹ 50,000 to ₹ 25,00,000
Repayment Tenure 12 to 60 Months
Collateral Requirement Zero (Unsecured)
Processing Horizon 24 to 72 Hours
Calculate Personal EMI

Home Loans — Mortgage Architecture & Affordability

Product Category: Secured Residential Mortgage
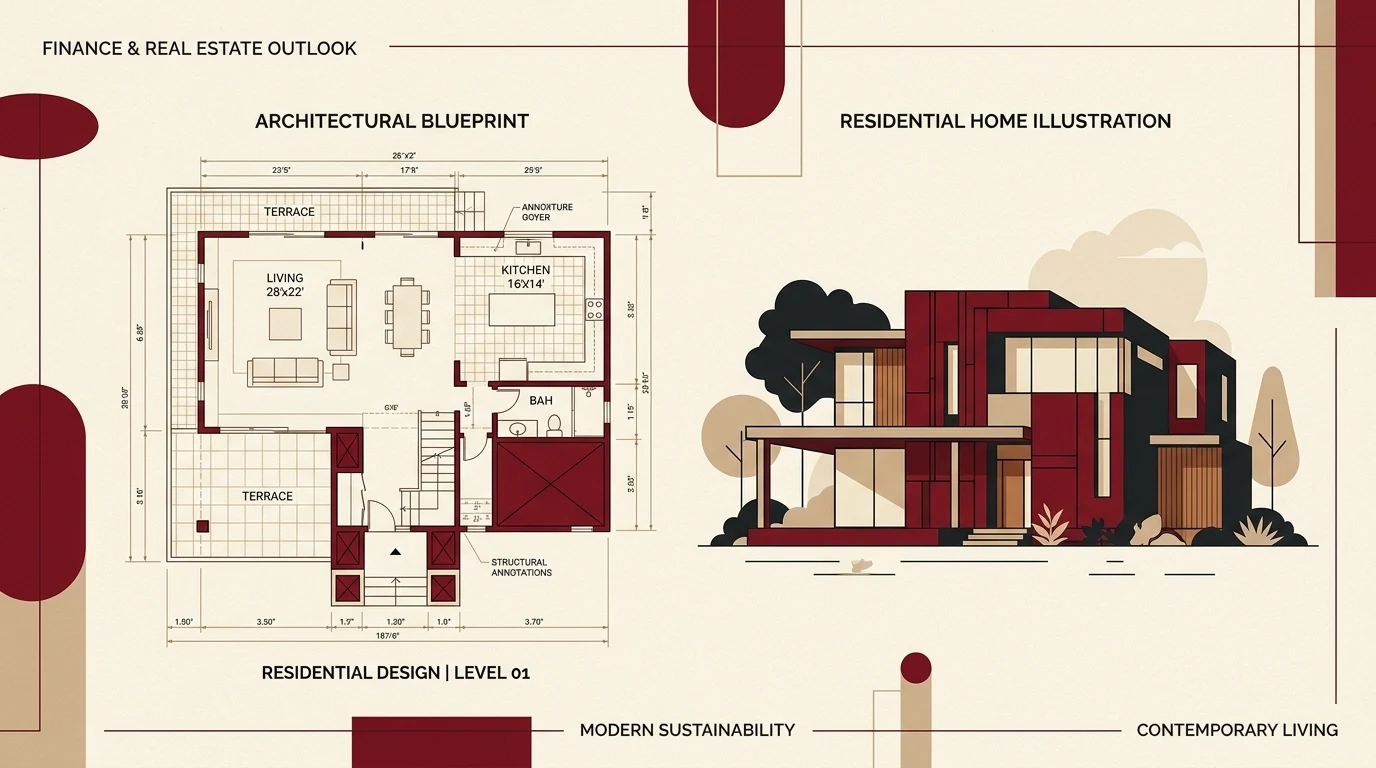
Modern Architecture and Home Loan Blueprint

Understanding Residential Mortgage Finance

Home loans represent the lowest-rate long-term financing available to consumers. The purchased property serves as primary mortgage security until all principal and interest payments are satisfied.

Affordability & Down Payment Guidelines

Prudent financial guidelines recommend contributing at least 20% of the property value as an upfront down payment. This mitigates over-leverage and eliminates higher insurance surcharges.

Tax Benefits Available

Under Indian income tax provisions (e.g. Section 80C and Section 24b), eligible borrowers can claim deductions on both principal repayments and annual interest disbursements up to statutory limits.

Tenure Span Up to 30 Years
Loan-to-Value (LTV) 75% to 90% of Cost
Security First Charge on Property
Rate Structure Floating (EBLR/MCLR) or Fixed
Model Mortgage EMI

Business Loans — Commercial Growth Capital

Product Category: Commercial Credit & Working Capital
Business Growth and Enterprise Financing

Fueling Commercial Enterprise Growth

Whether expanding storefronts, acquiring factory machinery, or managing seasonal working capital, business credit solutions are structured to align with corporate operating cash flows.

Key Underwriting Standards

  • Operational History: Minimum 2 to 3 years of continuous audited operations.
  • Turnover Thresholds: Verifiable annual revenue demonstrated through GST filings.
  • Profitability & Debt Service: Positive EBITDA and healthy interest coverage ratio (DSCR).
Financing Options Term Loan / OD Line / Machinery
Tenure Range 12 to 84 Months
Underwriting Basis Audited ITR & Banking
Check Business EMI

Education Loans — Higher Learning Financing

Product Category: Student Academic Credit
Higher Education and Student Loan Planning

Investing in Academic Careers

Education loans fund university tuition, laboratory equipment, university residence, and overseas travel for accredited degree programs in engineering, management, medicine, and research.

The Moratorium Period Advantage

Unlike standard commercial loans, education facilities include a repayment holiday (moratorium) spanning the duration of the degree course plus 6 to 12 months after graduation, allowing students to secure employment before repayment commences.

Coverage Tuition, Living & Travel
Repayment Start Course Completion + 6-12 Mo
Co-Signer Parent or Legal Guardian
Calculate Repayment

Understanding EMI, Principal Amortization & Total Interest Cost

Authored by Corvenzaar Research Desk • 6 Min Read

MATHEMATICAL ESSENTIALS

The Actuarial Mechanics of Equal Monthly Installments

An Equated Monthly Installment (EMI) represents a balanced mathematical mechanism designed to amortize debt over an agreed period. Behind the fixed monthly check lies a dynamic allocation shift between interest and principal.

The Reducing-Balance Formula

EMI = [P × r × (1 + r)^n] / [(1 + r)^n − 1]

Where P represents the principal, r equals the monthly interest rate (annual rate divided by 12 and 100), and n represents the total count of monthly installments.

Why Early Payments Go Primarily to Interest

In the opening months of any long tenure, outstanding principal is at its maximum peak. Consequently, the interest accrued on this massive principal accounts for 70% to 80% of your EMI. Only the small residual slice trims the actual loan principal.

As the principal is gradually chipped away over subsequent years, the monthly interest charge drops, causing a larger proportion of each installment to extinguish the remaining balance.

Actionable Takeaway: Make Early Lump-Sum Prepayments

Because interest is highest during the first third of your tenure, deploying annual bonuses or tax refunds toward principal prepayment during years 1 through 3 creates the most substantial long-term interest savings.

Fixed vs. Floating Interest Rates: Choosing the Right Risk Profile

Authored by Corvenzaar Research Desk • 4 Min Read

Fixed Rates: Absolute Cash Flow Certainty

A fixed-rate loan locks your interest rate across the designated term. Regardless of macro-economic inflation or policy rate tightening by the central bank, your monthly installment remains identical.

Pros: Predictable budgeting; immune to central bank rate hikes.
Cons: Lenders typically price fixed rates 1.5%–2.5% higher than prevailing floating benchmarks; borrowers do not benefit if interest rates decline.

Floating Rates: Market-Linked Flexibility

Floating loans are pegged directly to external benchmarks (such as the RBI Repo Rate, EBLR, or Treasury yields). When the benchmark fluctuates, your effective interest rate adjusts upward or downward.

Pros: Lower baseline interest rate; zero prepayment penalties for individual retail borrowers under regulatory mandates.
Cons: Monthly payments or loan tenures expand when monetary authorities hike benchmark interest rates.

How to Prepare for a Formal Loan Application & Protect Your Score

Authored by Corvenzaar Research Desk • 5 Min Read

1. Avoid the Hard Inquiry Trap

Each time you formally submit an application to a bank, the lender issues a "hard inquiry" to credit bureaus like CIBIL, Experian, or Equifax. Submitting multiple parallel applications within a few days signals credit distress and can lower your bureau score.

2. Audit Your Credit Report 60 Days Early

Download your authorized credit report at least two months prior to applying. Verify that past credit cards or resolved vehicle loans reflect accurately as "Closed" rather than "Settled" or "Overdue".

3. Streamline Operative Bank Statements

Underwriters inspect 6 months of primary bank statements to detect cheque bounces, minimum balance penalties, or irregular cash outflows. Keep your transaction accounts tidy and maintain a consistent positive balance buffer.

Hidden Loan Fees, Processing Costs & Legal Penalties Uncovered

Authored by Corvenzaar Research Desk • 4 Min Read

Looking Beyond the Advertised Interest Rate

A loan advertised at 9.5% can often carry an effective cost closer to 11% once all ancillary fees are accounted for. When negotiating loan sanctions, request an itemized breakdown of the following charges:

  • Processing Fee: Upfront charge ranging from 0.5% to 2.5% of the sanctioned amount. Always ask for fee concessions.
  • Document & Legal Vetting Fees: Common in mortgages for title search and technical site inspection.
  • Stamp Duty & CERSAI Charges: Statutory government fees for registering mortgage charges.
  • Bounce / Return Penalties: Substantial administrative charges incurred if auto-debit ECS instructions fail.